
This book provides a general introduction to Sequential Monte Carlo (SMC) methods, also known as particle filters. These methods have become a staple for the sequential analysis of data in such diverse fields as signal processing, epidemiology, machine learning, population ecology, quantitative finance, and robotics.
The coverage is comprehensive, ranging from the underlying theory to computational implementation, methodology, and diverse applications in various areas of science. This is achieved by describing SMC algorithms as particular cases of a general framework, which involves concepts such as Feynman-Kac distributions, and tools such as importance sampling and resampling. This general framework is used consistently throughout the book.
Extensive coverage is provided on sequential learning (filtering, smoothing) of state-space (hidden Markov) models, as this remains an important application of SMC methods. More recent applications, such as parameter estimation of these models (through e.g. particle Markov chain Monte Carlo techniques) and the simulation of challenging probability distributions (in e.g. Bayesian inference or rare-event problems), are also discussed.The book may be used either as a graduate text on Sequential Monte Carlo methods and state-space modeling, or as a general reference work on the area. Each chapter includes a set of exercises for self-study, a comprehensive bibliography, and a "Python corner," which discusses the practical implementation of the methods covered. In addition, the book comes with an open source Python library, which implements all the algorithms described in the book, and contains all the programs that were used to perform the numerical experiments.
| ISBN: | 9783030478476 |
| Publication date: | 3rd October 2021 |
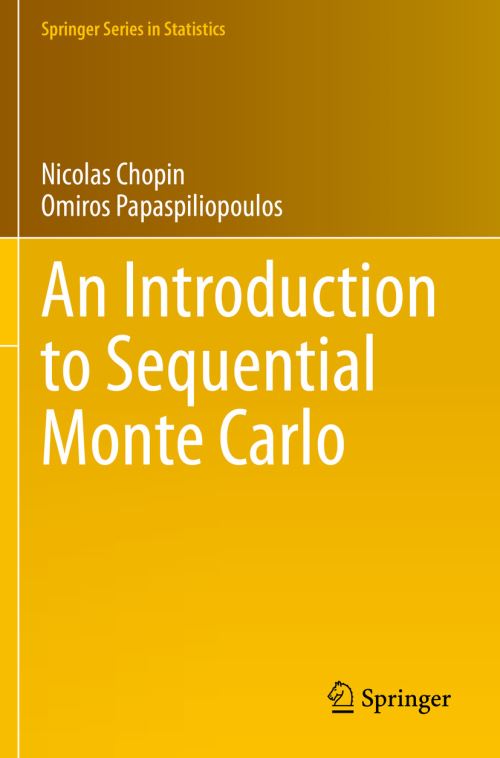
| Author: | Nicolas Chopin, Omiros Papaspiliopoulos |
| Publisher: | Springer an imprint of Springer International Publishing |
| Format: | Paperback |
| Pagination: | 340 pages |
| Series: | Springer Series in Statistics |
This book provides a general introduction to Sequential Monte Carlo (SMC) methods, also known as particle filters. These methods have become a staple for the sequential analysis of data in such diverse fields as signal processing, epidemiology, machine learning, population ecology, quantitative finance, and robotics.The coverage is comprehensive, ranging from the underlying theory to computational implementation, methodology, and diverse applications in various areas of science.
Paperback. £53.99, down from the £59.99 cover price. Not Available.
An Introduction to Sequential Monte Carlo was written by Nicolas Chopin, Omiros Papaspiliopoulos and published by Springer an imprint of Springer International Publishing
An Introduction to Sequential Monte Carlo has 340 pages
Yes it is part of Springer Series in Statistics series
£53.99, reduced from £59.99. Not Available.