
Since 1972 and the appearance of the famous Black & Scholes option pric- ing formula, derivatives have become an integrated part of everyday life in the financial industry. Options and derivatives are tools to control risk ex- posure, and used in the strategies of investors speculating in markets like fixed-income, stocks, currencies, commodities and energy. A combination of mathematical and economical reasoning is used to find the price of a derivatives contract.
This book gives an introduction to the theory of mathematical finance, which is the modern approach to analyse options and derivatives. Roughly speaking, we can divide mathematical fi- nance into three main directions. In stochastic finance the purpose is to use economic theory with stochastic analysis to derive fair prices for options and derivatives.
The results are based on stochastic modelling of financial as- sets, which is the field of empirical finance. Numerical approaches for finding prices of options are studied in computational finance. All three directions are presented in this book.
Algorithms and code for Visual Basic functions are included in the numerical chapter to inspire the reader to test out the theory in practice. The objective of the book is not to give a complete account of option theory, but rather relax the mathematical rigour to focus on the ideas and techniques.
| ISBN: | 9783540405023 |
| Publication date: | 26th November 2003 |
| Author: | Fred Espen Benth |
| Publisher: | Springer an imprint of Springer Berlin Heidelberg |
| Format: | Paperback |
| Pagination: | 162 pages |
| Series: | Universitext |
Since 1972 and the appearance of the famous Black & Scholes option pric- ing formula, derivatives have become an integrated part of everyday life in the financial industry. Options and derivatives are tools to control risk ex- posure, and used in the strategies of investors speculating in markets like fixed-income, stocks, currencies, commodities and energy.
Paperback. Not Available.
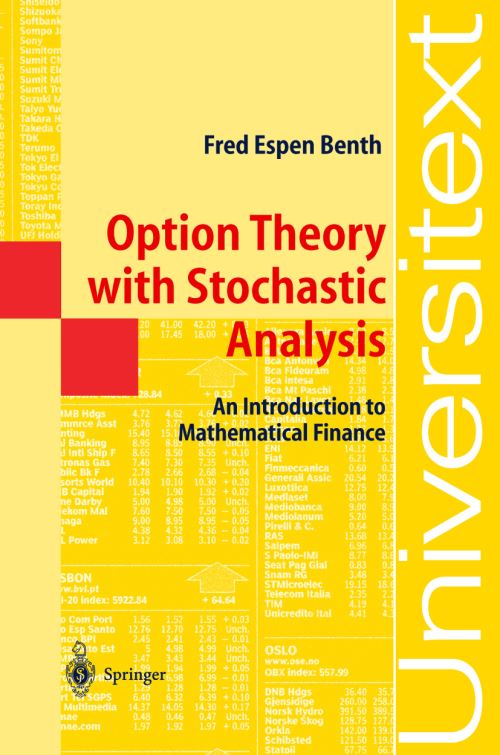
Option Theory With Stochastic Analysis was written by Fred Espen Benth and published by Springer an imprint of Springer Berlin Heidelberg
Option Theory With Stochastic Analysis has 162 pages
Yes it is part of Universitext series