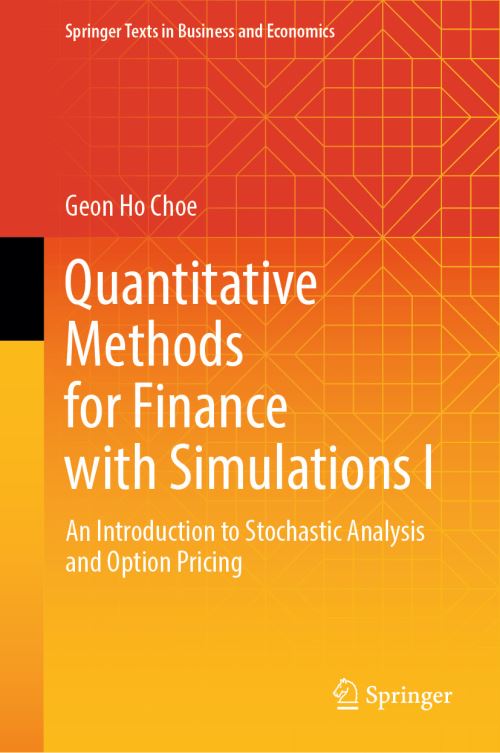
This self-contained book is the first of a two-volume set providing a thorough introduction to quantitative finance, covering both theoretical and computational methods.
This volume covers stochastic analysis, option pricing theory, optimal portfolio investment, and bond pricing. Computer simulations in Matlab and Python are provided to illustrate theoretical ideas. Background in mathematics is included in the appendices and the level of familiarity with computer programming is kept to a minimum.
| ISBN: | 9783032123268 |
| Publication date: | 7th September 2026 |
| Author: | Geon Ho Choe |
| Publisher: | Springer an imprint of Springer Nature Switzerland |
| Format: | Hardback |
| Pagination: | 601 pages |
| Series: | Springer Texts in Business and Economics |
This self-contained book is the first of a two-volume set providing a thorough introduction to quantitative finance, covering both theoretical and computational methods. This volume covers stochastic analysis, option pricing theory, optimal portfolio investment, and bond pricing. Computer simulations in Matlab and Python are provided to illustrate theoretical ideas.
Hardback. £58.49, down from the £64.99 cover price. Not Available.
Quantitative Methods for Finance With Simulations. I An Introduction to Stochastic Analysis and Option Pricing was written by Geon Ho Choe and published by Springer an imprint of Springer Nature Switzerland
Quantitative Methods for Finance With Simulations. I An Introduction to Stochastic Analysis and Option Pricing has 601 pages
Yes it is part of Springer Texts in Business and Economics series
£58.49, reduced from £64.99. Not Available.