This textbook is second edition of the highly used earlier text containing the same topics, divided similarly into four parts, but with major revisions and using STATA 18 and R (previous version used STATA 15.1). Part I is a discussion on introductory econometric methods covering the syllabus of econometrics at the graduate level courses. This part of the book provides an introduction to basic econometric methods for data analysis that economists and other social scientists use to estimate the economic and social relationships, and to test hypotheses about them, using real-world data. There are five chapters in this section covering the data management issues, details of linear regression models, the related problems due to violation of the classical assumptions, regression diagnostics and regression analysis with qualitative regressors.
Part II covers some advanced topics used frequently in empirical study with cross section data. This part contains three chapters to include the problems of endogeneity and instrumental variable regression, and models with limited dependent variables. Special emphasis is given to the econometric models with qualitative and limited dependent variables because of its popularity in empirical research with cross section data.
Part III deals with time series econometric analysis. Time series data have some special features and they should be handled extremely cautiously. This book covers extensively both the univariate and multivariate time series econometric models and their applications with software programming in six chapters.
Part IV takes care of panel data analysis in four chapters. Different aspects of fixed effects and random effects are discussed here. This part extends panel data analysis by taking dynamic panel data models which are most suitable for macroeconomic research.
All chapters in this book are the applications of econometric models by using Stata 18 and R. Simple presentation of some difficult topics in a rigorous manner is the major strength of this book. The topics covered in this book are basics and necessary for econometrics training of every student in economics.
In this edition, each chapter has been addressed in more compact manner by incorporating some additional topics. The book thus aims to enhance their interest on empirical research in economics and other fields of social science.
| ISBN: | 9789819572250 |
| Publication date: | 23rd June 2026 |
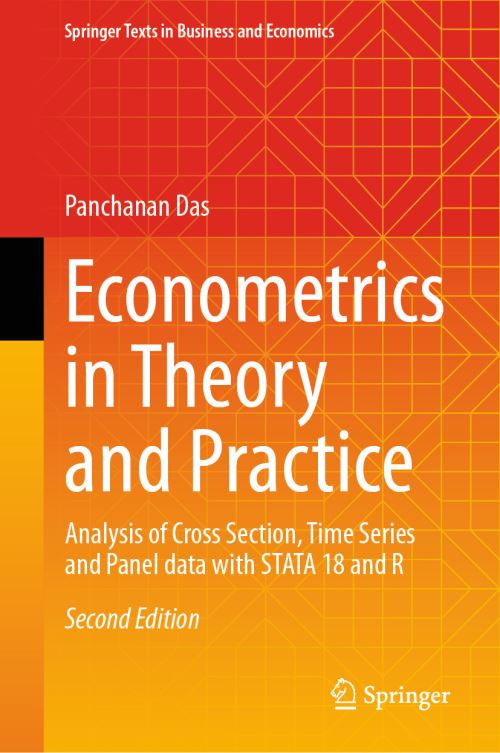
| Author: | Panchanan Das |
| Publisher: | Springer an imprint of Springer Nature Singapore |
| Format: | Hardback |
| Pagination: | 481 pages |
| Series: | Springer Texts in Business and Economics |
This textbook is second edition of the highly used earlier text containing the same topics, divided similarly into four parts, but with major revisions and using STATA 18 and R (previous version used STATA 15.1). Part I is a discussion on introductory econometric methods covering the syllabus of econometrics at the graduate level courses. This part of the book provides an introduction to basic econometric methods for data analysis that economists and other social scientists use to estimate the economic and social relationships, and to test hypotheses about them, using real-world data.
Hardback. £80.99, down from the £89.99 cover price. Not Available.
Econometrics in Theory and Practice was written by Panchanan Das and published by Springer an imprint of Springer Nature Singapore
Econometrics in Theory and Practice has 481 pages
Yes it is part of Springer Texts in Business and Economics series
£80.99, reduced from £89.99. Not Available.